
CRD IV/CRR own funds and capital requirements, A0
Herausgeber:
PricewaterhouseCoopers GmbH Wirtschaftsprüfungsgesellschaft
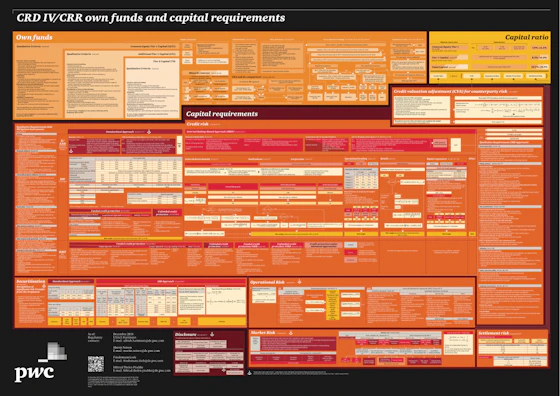
Ein Überblick über die CRD IV/CRR-Eigenkapitalanforderungen und Berechnungsmethoden für Banken in der EU.
Berechnung von Eigenkapitalquoten mit CET1-, AT1- und Tier-2-Kapitalinstrumenten
Standardisierte und interne Ratingverfahren zur Bestimmung risikogewichteter Aktiva
Kreditrisiko-, Operationalrisiko- und Marktrisiko-Berechnungsmethoden für Banken
zzgl. USt. (wird beim Checkout hinzugefügt)
Jahr:
2014
Sprache:
Englisch
Seiten:
1
Datei Format:
Auszug
To bring the global regulatory standards on bank capital adequacy and liquidity of the Basel Committee on Banking Supervision into European law, the European Commission has drafted its Capital Requirements Directive “CRD IV”. The poster "CRD IV Own funds and capital requirements" by PwC shows the relations between global framework “Basel III”, the proposed European and national regulation and offers orientation in an ever more complex regulatory environment. Included are the requirements of the Basel III framework as well as regulatory requirements for securitisation, market risk, operational risk, and CVA-risk.