
CRD IV/CRR own funds and capital requirements, A0
Publisher:
PricewaterhouseCoopers GmbH Wirtschaftsprüfungsgesellschaft
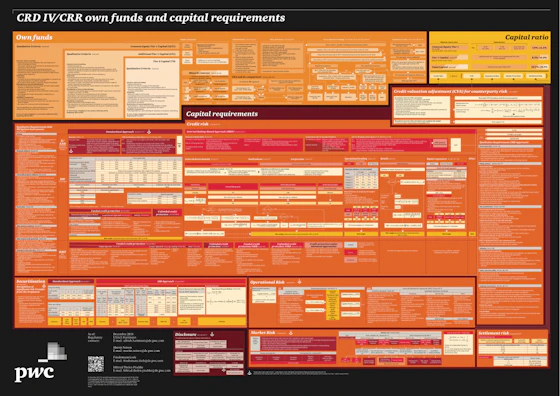
A reference to the capital ratios, risk calculations, and regulatory requirements banks must apply under CRD IV/CRR.
Capital ratio calculations combining common equity tier 1, additional tier 1, and tier 2 capital with minimum thresholds
Standardized and internal ratings-based approaches for assessing credit risk and determining risk-weighted assets
Treatment rules for corporate loans, retail mortgages, securitizations, derivatives, and collateral recognition
excl. VAT (added at checkout)
Year:
2014
Language:
English
Pages:
1
File Format:
Abstract
To bring the global regulatory standards on bank capital adequacy and liquidity of the Basel Committee on Banking Supervision into European law, the European Commission has drafted its Capital Requirements Directive “CRD IV”. The poster "CRD IV Own funds and capital requirements" by PwC shows the relations between global framework “Basel III”, the proposed European and national regulation and offers orientation in an ever more complex regulatory environment. Included are the requirements of the Basel III framework as well as regulatory requirements for securitisation, market risk, operational risk, and CVA-risk.